FHA
Active
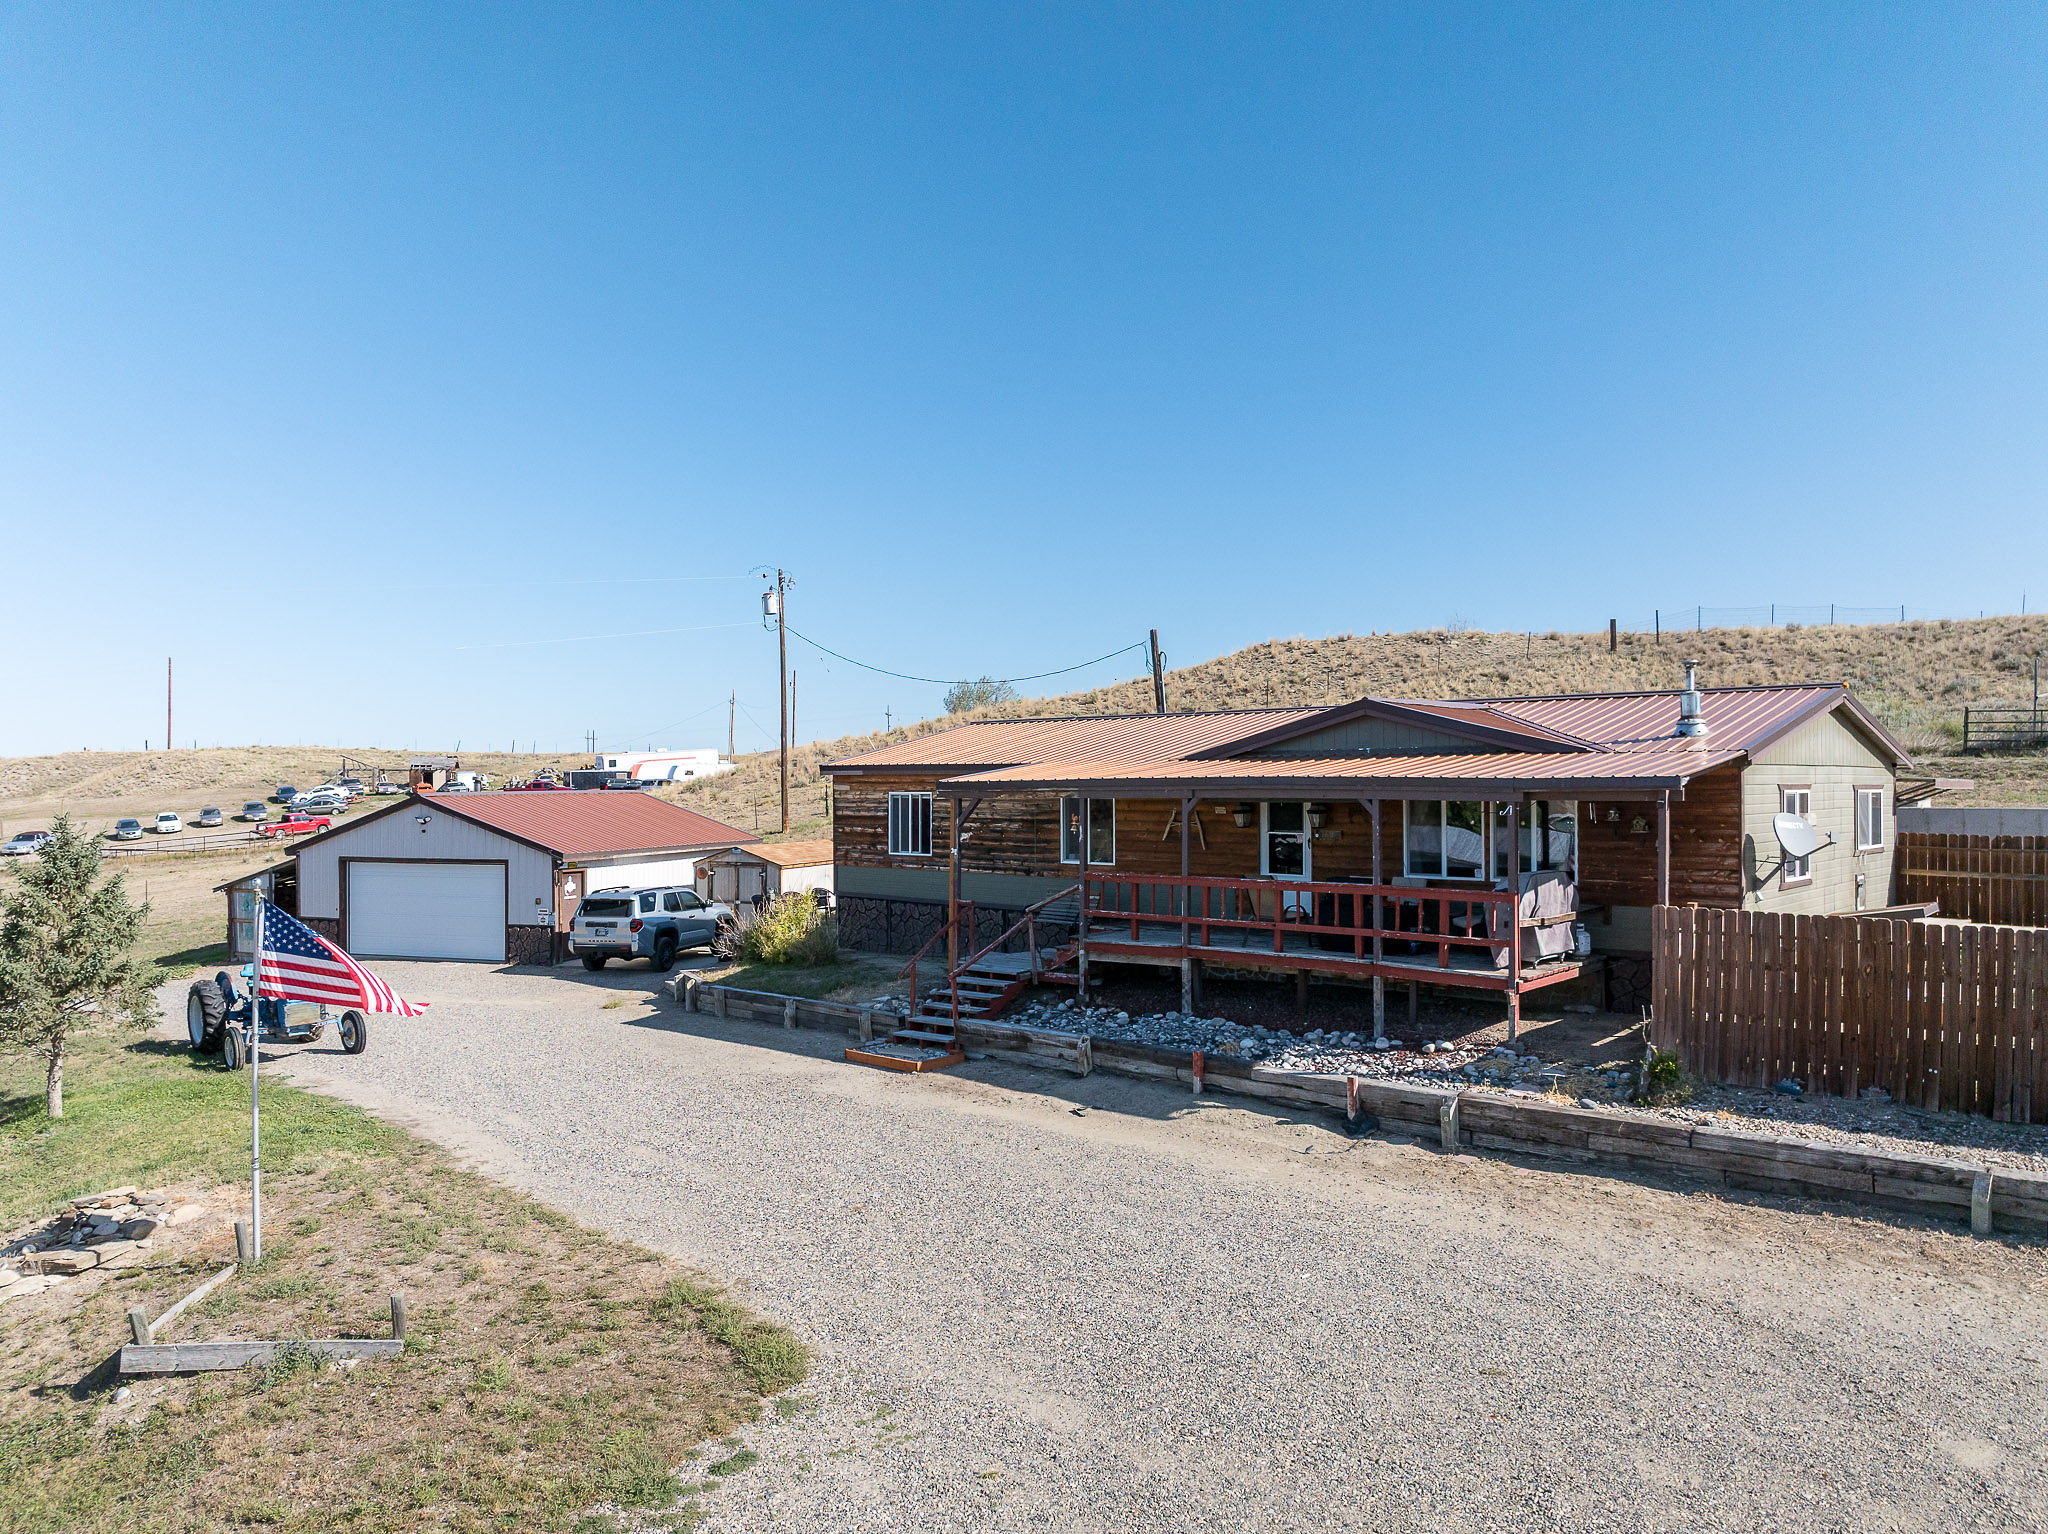
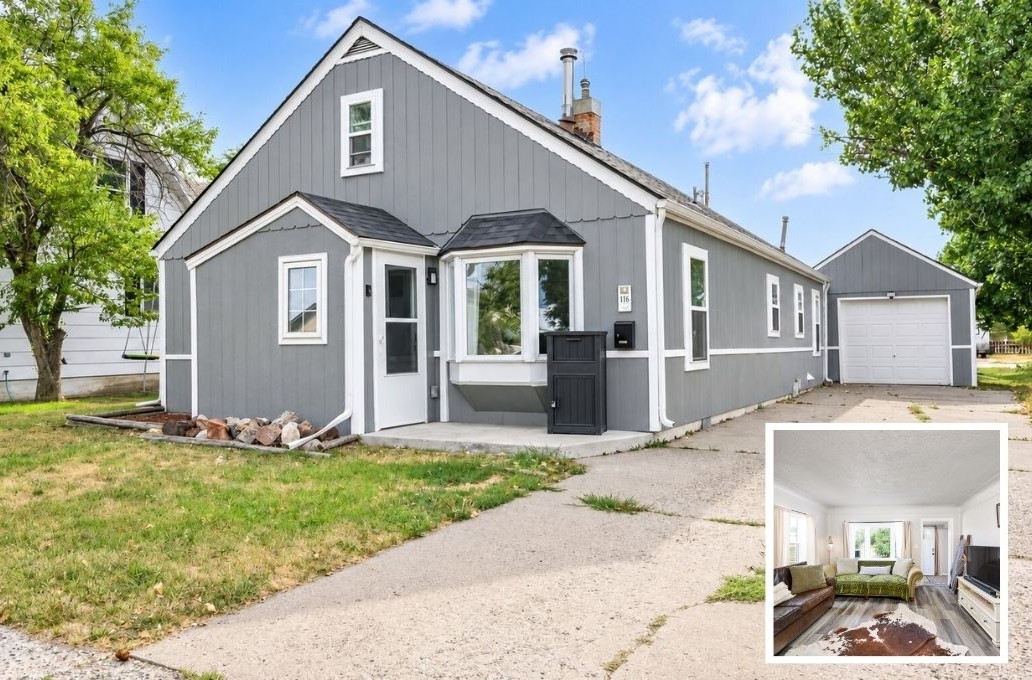
15$370,000$175,871 equity gap
- Rate
- 3.02%
7.40%today- Payment
- $925/mo
$1,515today
- 3beds
- 2baths
- 1,620sqft
Montana · Statewide
227 homes in Montana carry an existing FHA, VA, or USDA loan you can take over, with locked rates from 2.20%. Assume the seller’s mortgage instead of financing at today’s 7.2%.
Live MLS data · Updated
Montana assumable market
by the numbers.
Ranked by live assumable inventory. Every city is its own market page with local listings, rates, ZIP codes, and cash-to-assume figures.
Search all of Montana on the mapAlso covered in Montana, no verified assumable listings today:
Every number on this page comes from the live MLS feeds UMe indexes across Montana. Updated October 2026.
How assumptions work for buyersMontana has 227 homes for sale with an assumable mortgage as of October 2026: 146 VA loans and 81 FHA loans that a qualified buyer can take over at the seller's existing rate instead of financing at today's roughly 7.2%. Rates on active Montana assumable listings start at 2.20% with a median of 4.98%; 93 listings are under 4% and 117 are under 5%.
The median assumable home in Montana lists for $549,000, with a median of $211,436 in cash to assume, the gap between the price and the remaining loan balance. At the median assumable rate the principal-and-interest payment is about $1,613 a month versus $2,224 for the same balance at today's rate, roughly $612 kept every month and $7,344 a year. The deepest Montana inventory is in Kalispell (32), Great Falls (26), Helena (23), Missoula (12), and Butte (11).
UMe confirms the balance, rate, and assumability of each listing with the listing agent before marking it Certified. FHA, VA, and USDA loans are assumable by law, and you do not need to be a veteran to assume a VA loan. Once you are under contract, the loan servicer underwrites you rather than a new lender; most Montana assumptions close in 45 to 90 days, and UMe tracks the file with the servicer and both agents so nothing stalls.

Live MLS collection. Loan balances, payment estimates, and cash-to-assume amounts update with the source listing. Taxes, insurance, HOA, closing costs, and secondary financing may change the final monthly payment.
Live counts from the MLS feeds we index for Montana. Updated October 2026.
FHA, VA, and USDA loans are assumable by law. Conventional loans almost never are.
The sliders start at the median Montana assumable listing: $549,000 list price and a 4.98% existing rate. We compare the payment you would take over against financing the same balance with a new loan at today’s 7.20%. Principal and interest only; taxes, insurance, and HOA dues are the same either way.
The gap between price and balance is the seller’s equity: your cash to assume, or what a second loan can help cover.
38% of the price. Eligible buyers can start with as little as 5% down using a second loan for the rest.
Estimates for illustration. The real numbers depend on the loan, the servicer, and your qualification; every Montana listing on UMe shows the actual balance, rate, and payment.
You’re not applying for a new mortgage. You’re stepping into one that already exists, at the rate it was written. Four steps, and UMe owns the hard one.
Start with pre-qualificationEvery listing on this page carries an existing FHA, VA, or USDA loan. Filter the Montana map by existing rate, monthly payment, or cash to assume instead of by list price alone.
You pay the seller the difference between the price and the remaining balance, a median of $211,436 in Montana today. Cash, a second loan, or seller financing can bridge it.
The current loan servicer reviews your credit, income, and debt just like a lender would. UMe prepares the file, works the servicer directly, and chases every follow-up so the 45-to-90-day timeline holds.
The seller’s balance, rate, and remaining term become yours. No points, no origination fee, no reset to 30 years, and a Montana payment written in a different decade.
The numbers below come from current Montana inventory and update as listings change.
All assumption FAQsAs of October 2026, UMe tracks 227 active assumable listings in Montana. Inventory refreshes from the MLS throughout the day, so the map may show slightly different counts.
Current Montana inventory breaks down as VA (146, median 4.21%) and FHA (81, median 6.11%). FHA, VA, and USDA mortgages are assumable by law, which is why they make up nearly all assumable listings. Conventional loans usually carry a due-on-sale clause and cannot be assumed. You do not need to be a veteran to assume a VA loan, though the seller's entitlement stays tied up unless you substitute your own.
The lowest rate on an active Montana assumable listing is 2.20%, and the median across all 227 listings is 4.98%. 93 listings are under 4% and 117 are under 5%, compared with roughly 7.2% for a new 30-year loan today.
Across current Montana listings, the median principal-and-interest payment on the assumable loan is $1,613 per month versus $2,224 for the same balance at today's rates, a difference of about $612 every month, or $7,344 a year. The savings compound because you also keep the seller's remaining term instead of restarting a 30-year clock.
When you assume a loan you pay the seller the difference between the list price and the remaining loan balance. In Montana that gap is currently a median of $211,436 on a median list price of $549,000. Buyers cover it with cash, a second mortgage, or seller financing; UMe can connect you with lenders who write gap loans behind an assumption.
The deepest assumable inventory in Montana is in Kalispell (32), Great Falls (26), Helena (23), Missoula (12), and Butte (11). Each city has its own page with live counts, rates, and neighborhoods, and the Montana map lets you search the whole state at once.
Most FHA and VA assumptions close in 45 to 90 days. The loan servicer, not a new lender, underwrites you, and servicer turnaround is the main variable. UMe tracks the file with the servicer and the listing agent so nothing stalls, and every listing shows whether the assumption has already been confirmed with the seller's side.
Every listing on the Montana map has a rate you can take over. Start with the cities holding the deepest inventory, get pre-qualified in minutes, and let UMe carry the assumption to closing.